Buy posl.eu ?
We are moving the project
posl.eu .
Are you interested in purchasing the domain
posl.eu ?
domain@kv-gmbh.de · 0541-91531010
Buy posl.eu ?
How are sales and accounting related?
Sales and accounting are closely related as sales data is used by accountants to record revenue and track financial transactions. Accountants use sales information to prepare financial statements, such as income statements and balance sheets, which provide insights into the financial health of a business. Additionally, accurate accounting practices ensure that sales revenue is properly recorded and that expenses are correctly accounted for, leading to a more transparent and reliable financial reporting process. Ultimately, the collaboration between sales and accounting departments is essential for maintaining the financial integrity of a business. **
What are the accounting entries in the field of accounting for inventory valuation?
In the field of accounting, inventory valuation involves recording the cost of goods held for sale. The accounting entries for inventory valuation typically include debiting the inventory account to reflect the cost of goods purchased or produced, and crediting the corresponding account such as accounts payable or cash. Additionally, adjustments may be made to account for any changes in the value of inventory, such as writing down inventory to its lower of cost or market value. These adjustments are recorded by debiting cost of goods sold and crediting inventory reserve or loss account. **
Similar search terms for Accounting
Top-Angebote
Products related to Accounting:
-
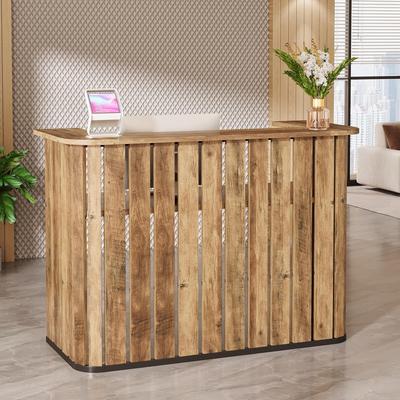
BLUEBELL "63"" Reception Desk with Counter, Modern U-Shaped Front Desk, Retail Checkout Counter Table"Enhance your reception area or office workspace with this 63-inch modern U-shaped reception desk, designed to combine style, functionality, and privacy.255,99 $*Shipping: 0,00 $Secure redirect to the provider
-
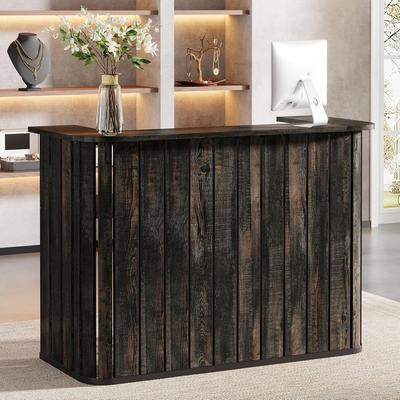
"WESOME 94.5"" Front Desk Reception Desk with Drawer, Computer Workstation for Checkout, Lobby, Office, Retail Store"Upgrade your commercial space or home interior with our 94.5-inch Multifunctional Reception & Bar Desk, a perfect blend of modern aesthetics, practical functionality, and versatile usability.1858,99 $*Shipping: 0,00 $Secure redirect to the provider
-
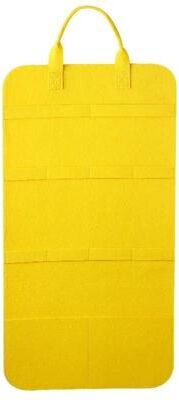
Uplifted Finds Vertical Toy Inventory Management Module grayOptimize your pets engagement ecosystem with the Vertical ToyInventory Module, a professionalgrade organization system engineered with spatialefficiency logic. This highutility module features a multitier felt architecture specifically designed to...92,97 $*Shipping: 0,00 $Secure redirect to the provider
-
Uplifted Finds Vertical Toy Inventory Management Module greenOptimize your pets engagement ecosystem with the Vertical ToyInventory Module, a professionalgrade organization system engineered with spatialefficiency logic. This highutility module features a multitier felt architecture specifically designed to...92,97 $*Shipping: 0,00 $Secure redirect to the provider

-
How is inventory valuation done in accounting?
Inventory valuation in accounting is done using different methods such as First-In-First-Out (FIFO), Last-In-First-Out (LIFO), and Weighted Average Cost. These methods determine the cost of goods sold and the value of ending inventory. FIFO assumes that the oldest inventory items are sold first, while LIFO assumes that the newest inventory items are sold first. Weighted Average Cost calculates the average cost of all units in inventory. The chosen method can have a significant impact on a company's financial statements and tax liabilities. **
-
Does the inventory in accounting not match the target inventory?
If the inventory in accounting does not match the target inventory, it could indicate potential issues such as theft, errors in recording transactions, or discrepancies in the physical counting of inventory. It is important to investigate the root cause of the discrepancy and take corrective actions to reconcile the inventory. This may involve conducting a physical inventory count, reviewing transaction records, and implementing better inventory management practices to prevent future discrepancies. Regular monitoring and reconciliation of inventory can help ensure accurate accounting records and prevent potential losses. **
-
Is there a subject in the training to become a management assistant for office management that covers accounting or financial accounting?
Yes, typically in the training to become a management assistant for office management, there is a subject that covers accounting or financial accounting. This subject is important for management assistants as they often handle financial tasks such as budgeting, invoicing, and financial reporting. Understanding accounting principles and financial statements is crucial for effectively managing office finances and supporting the organization's financial goals. **
-
What are the journal entries in accounting for inventory valuation?
The journal entries in accounting for inventory valuation typically involve recording the cost of inventory on the balance sheet. When inventory is purchased, the entry would debit the inventory account and credit the accounts payable or cash account. When inventory is sold, the cost of goods sold account is debited and the inventory account is credited for the cost of the items sold. Additionally, adjustments may be made to the inventory account to reflect changes in the value of inventory, such as write-downs for obsolete or damaged goods. **
What are the accounting terms of cost accounting?
Cost accounting involves several key terms, including direct costs, indirect costs, fixed costs, variable costs, and overhead. Direct costs are expenses directly tied to the production of a specific product or service, while indirect costs are not directly tied to a specific product or service. Fixed costs remain constant regardless of production levels, while variable costs fluctuate with production levels. Overhead includes all indirect costs incurred in the production process, such as rent, utilities, and administrative expenses. Understanding and accurately tracking these cost accounting terms is essential for businesses to effectively manage their expenses and make informed financial decisions. **
What is a cost center accounting form in accounting?
A cost center accounting form is a document used to track and record the expenses incurred by a specific department or cost center within an organization. It helps in monitoring and controlling costs associated with a particular area of the business. The form typically includes details such as the date of the expense, description of the cost, amount spent, and the cost center to which the expense is allocated. By using cost center accounting forms, businesses can analyze the financial performance of each department and make informed decisions to improve efficiency and profitability. **
Top-Angebote
Products related to Accounting:
-
Uplifted Finds Vertical Toy Inventory Management Module yellowOptimize your pets engagement ecosystem with the Vertical ToyInventory Module, a professionalgrade organization system engineered with spatialefficiency logic. This highutility module features a multitier felt architecture specifically designed to...92,97 $*Shipping: 0,00 $Secure redirect to the provider
-
Bluebell Reception Desk with Counter, Retail Checkout Counter Table, Modern Front DeskThis contemporary reception desk, with its U-shaped design, provides both aesthetic appeal and privacy. Designed for optimal efficiency, it has a double-tier structure for easy access to essentials and it is ergonomically high for comfort.204,74 $*Shipping: 0,00 $Secure redirect to the provider
-
BLUEBELL "63"" Reception Desk with Counter, Modern U-Shaped Front Desk, Retail Checkout Counter Table"Enhance your reception area or office workspace with this 63-inch modern U-shaped reception desk, designed to combine style, functionality, and privacy.255,99 $*Shipping: 0,00 $Secure redirect to the provider
-
"WESOME 94.5"" Front Desk Reception Desk with Drawer, Computer Workstation for Checkout, Lobby, Office, Retail Store"Upgrade your commercial space or home interior with our 94.5-inch Multifunctional Reception & Bar Desk, a perfect blend of modern aesthetics, practical functionality, and versatile usability.1858,99 $*Shipping: 0,00 $Secure redirect to the provider
-
How are sales and accounting related?
Sales and accounting are closely related as sales data is used by accountants to record revenue and track financial transactions. Accountants use sales information to prepare financial statements, such as income statements and balance sheets, which provide insights into the financial health of a business. Additionally, accurate accounting practices ensure that sales revenue is properly recorded and that expenses are correctly accounted for, leading to a more transparent and reliable financial reporting process. Ultimately, the collaboration between sales and accounting departments is essential for maintaining the financial integrity of a business. **
-
What are the accounting entries in the field of accounting for inventory valuation?
In the field of accounting, inventory valuation involves recording the cost of goods held for sale. The accounting entries for inventory valuation typically include debiting the inventory account to reflect the cost of goods purchased or produced, and crediting the corresponding account such as accounts payable or cash. Additionally, adjustments may be made to account for any changes in the value of inventory, such as writing down inventory to its lower of cost or market value. These adjustments are recorded by debiting cost of goods sold and crediting inventory reserve or loss account. **
-
How is inventory valuation done in accounting?
Inventory valuation in accounting is done using different methods such as First-In-First-Out (FIFO), Last-In-First-Out (LIFO), and Weighted Average Cost. These methods determine the cost of goods sold and the value of ending inventory. FIFO assumes that the oldest inventory items are sold first, while LIFO assumes that the newest inventory items are sold first. Weighted Average Cost calculates the average cost of all units in inventory. The chosen method can have a significant impact on a company's financial statements and tax liabilities. **
-
Does the inventory in accounting not match the target inventory?
If the inventory in accounting does not match the target inventory, it could indicate potential issues such as theft, errors in recording transactions, or discrepancies in the physical counting of inventory. It is important to investigate the root cause of the discrepancy and take corrective actions to reconcile the inventory. This may involve conducting a physical inventory count, reviewing transaction records, and implementing better inventory management practices to prevent future discrepancies. Regular monitoring and reconciliation of inventory can help ensure accurate accounting records and prevent potential losses. **
Similar search terms for Accounting
-
Uplifted Finds Vertical Toy Inventory Management Module grayOptimize your pets engagement ecosystem with the Vertical ToyInventory Module, a professionalgrade organization system engineered with spatialefficiency logic. This highutility module features a multitier felt architecture specifically designed to...92,97 $*Shipping: 0,00 $Secure redirect to the provider
-
Uplifted Finds Vertical Toy Inventory Management Module greenOptimize your pets engagement ecosystem with the Vertical ToyInventory Module, a professionalgrade organization system engineered with spatialefficiency logic. This highutility module features a multitier felt architecture specifically designed to...92,97 $*Shipping: 0,00 $Secure redirect to the provider
-
Uplifted Finds Vertical Toy Inventory Management Module pinkOptimize your pets engagement ecosystem with the Vertical ToyInventory Module, a professionalgrade organization system engineered with spatialefficiency logic. This highutility module features a multitier felt architecture specifically designed to...92,97 $*Shipping: 0,00 $Secure redirect to the provider
-
Uplifted Finds Vertical Toy Inventory Management Module sky BlueOptimize your pets engagement ecosystem with the Vertical ToyInventory Module, a professionalgrade organization system engineered with spatialefficiency logic. This highutility module features a multitier felt architecture specifically designed to...92,97 $*Shipping: 0,00 $Secure redirect to the provider
-
Is there a subject in the training to become a management assistant for office management that covers accounting or financial accounting?
Yes, typically in the training to become a management assistant for office management, there is a subject that covers accounting or financial accounting. This subject is important for management assistants as they often handle financial tasks such as budgeting, invoicing, and financial reporting. Understanding accounting principles and financial statements is crucial for effectively managing office finances and supporting the organization's financial goals. **
-
What are the journal entries in accounting for inventory valuation?
The journal entries in accounting for inventory valuation typically involve recording the cost of inventory on the balance sheet. When inventory is purchased, the entry would debit the inventory account and credit the accounts payable or cash account. When inventory is sold, the cost of goods sold account is debited and the inventory account is credited for the cost of the items sold. Additionally, adjustments may be made to the inventory account to reflect changes in the value of inventory, such as write-downs for obsolete or damaged goods. **
-
What are the accounting terms of cost accounting?
Cost accounting involves several key terms, including direct costs, indirect costs, fixed costs, variable costs, and overhead. Direct costs are expenses directly tied to the production of a specific product or service, while indirect costs are not directly tied to a specific product or service. Fixed costs remain constant regardless of production levels, while variable costs fluctuate with production levels. Overhead includes all indirect costs incurred in the production process, such as rent, utilities, and administrative expenses. Understanding and accurately tracking these cost accounting terms is essential for businesses to effectively manage their expenses and make informed financial decisions. **
-
What is a cost center accounting form in accounting?
A cost center accounting form is a document used to track and record the expenses incurred by a specific department or cost center within an organization. It helps in monitoring and controlling costs associated with a particular area of the business. The form typically includes details such as the date of the expense, description of the cost, amount spent, and the cost center to which the expense is allocated. By using cost center accounting forms, businesses can analyze the financial performance of each department and make informed decisions to improve efficiency and profitability. **
* All prices are inclusive of VAT and, if applicable, plus shipping costs. The offer information is based on the details provided by the respective shop and is updated through automated processes. Real-time updates do not occur, so deviations can occur in individual cases. ** Note: Parts of this content were created by AI.